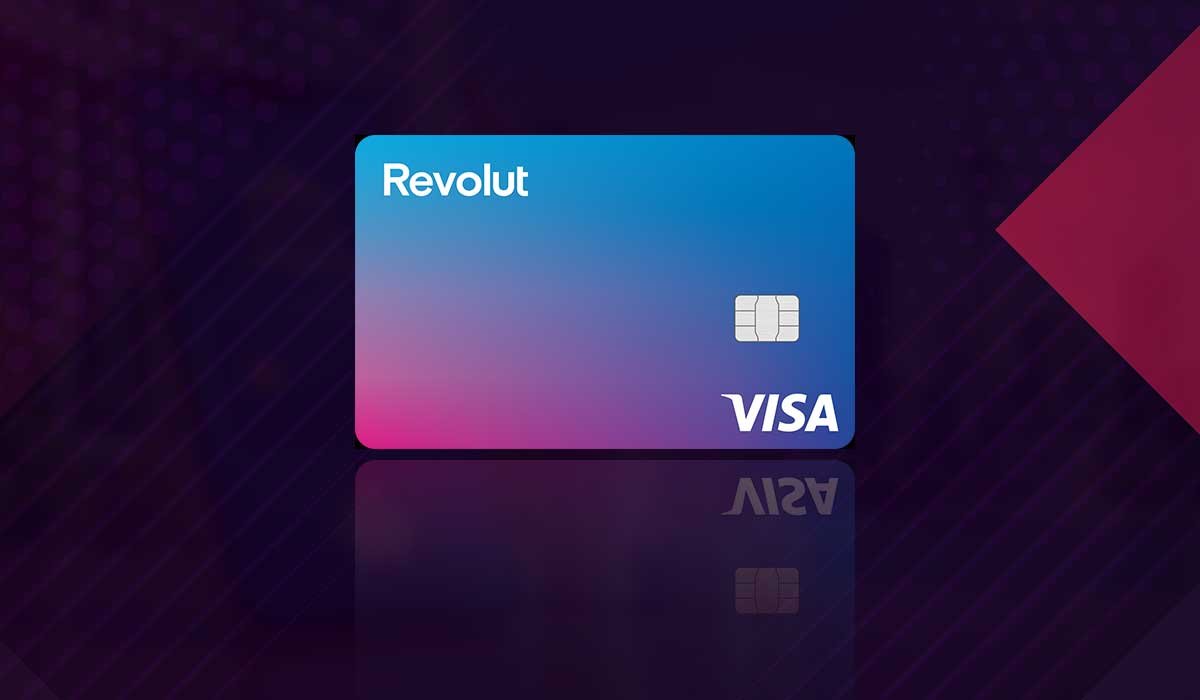
New Zealand’s banking sector has welcomed a significant new entrant, with international financial technology company Revolut officially registered as a bank in New Zealand. The development marks an important milestone for the company and could bring more competition to a market traditionally dominated by major established banking groups.
The Reserve Bank of New Zealand (RBNZ) confirmed the registration on 3 November 2026, making Revolut the country’s 27th registered bank. The move gives the fintech company a pathway to expand its local banking services, including interest-paying savings accounts and a broader range of financial products.
For New Zealand consumers, the announcement raises an important question: could the arrival of another digital banking option change the way Kiwis manage their money?
Related Post
Revolut Officially Enters New Zealand’s Registered Banking Sector
Revolut has operated in New Zealand since July 2023, providing financial services through its existing local business. The new registration represents a major step forward in its plans to establish a broader presence in the country’s banking industry.
The company, which was founded in the United Kingdom, has built its international reputation around app-based financial services, offering customers digital tools for managing money and making payments.
With its New Zealand banking registration, Revolut can develop its local offering further within the applicable regulatory framework. Its entry could introduce another competitor for customers who want convenient access to everyday banking and savings services.
According to the Reserve Bank, the registration was granted under the Banking (Prudential Supervision) Act 1989. The approval followed the regulatory assessment required for an organisation seeking registered bank status in New Zealand.
The milestone also places Revolut among the registered banks listed by the country’s central bank.
What Does Revolut’s Banking Registration Mean for Kiwis?
For consumers, the most significant impact could be the expansion of banking choices.
New Zealand’s financial services market includes long-established banks with extensive branch networks, digital banking platforms and established customer relationships. A new entrant operating with a digital-first approach could encourage providers to compete more actively on convenience, product features and customer experience.
Revolut has indicated that its banking operation will introduce additional products, including interest-paying savings accounts and a wider range of credit services.
These developments could appeal to customers who prefer managing their finances through a mobile application rather than visiting a branch.
However, a new bank does not automatically mean that every customer will benefit immediately. The value of any new offering will depend on its fees, interest rates, eligibility rules, customer support and the practical features available to account holders.
Consumers should compare the actual terms of available products before deciding whether to change providers.
Savings Accounts Could Be an Important Attraction
Savings products are likely to be one of the key areas to watch as Revolut develops its New Zealand banking business.
The company has announced the rollout of Instant Access Savings accounts, including an introductory variable interest rate of 3.50% per annum for eligible new retail customers during their first four months. The offer is subject to the provider’s terms and conditions, and introductory rates can change.
The account is designed to give eligible customers access to savings while earning interest, with daily interest payments and no withdrawal penalties advertised by Revolut.
For people building an emergency fund, saving for a home deposit or setting aside money for future expenses, an accessible savings account can be a useful part of a wider financial plan.
Nevertheless, customers should look beyond the headline rate. Important considerations include the interest rate that applies after the introductory period, any account conditions, how interest is calculated and whether there are limits or eligibility requirements.
A competitive introductory offer can be attractive, but the ongoing rate and overall account terms matter just as much.
What About Credit Cards and Other Lending Products?
The banking registration also opens the way for Revolut to explore a broader range of financial products in New Zealand, including credit-related services.
Credit cards and other lending products may become part of the company’s longer-term offering, but customers should not assume that every product will be available immediately simply because the bank has been registered.
Availability, launch dates, interest rates, fees, credit limits and approval requirements need to be confirmed through official product announcements.
For consumers considering a credit card, the most important factors remain the interest rate, annual fees, repayment conditions, rewards structure and charges that may apply when a balance is not paid in full.
Digital application processes can make financial products easier to access, but borrowing decisions should still be based on affordability and individual circumstances.
Could Revolut Challenge New Zealand’s Established Banks?
New Zealand’s banking sector has historically been dominated by major banking groups, including organisations associated with Australia’s largest banks. Entering this market presents an opportunity for Revolut, but building a sustainable customer base will require more than an app and attractive promotional offers.
Customers often value reliability, transparent fees, responsive customer service and confidence that their money is being handled appropriately. Existing banks also have established systems for mortgages, business lending, everyday accounts and other services.
A digital-first competitor could put additional pressure on providers to improve their online services, simplify account management and make pricing easier to understand.
Competition may also encourage consumers to review their existing banking arrangements instead of automatically staying with the same provider for years.
However, the long-term effect will depend on how Revolut develops its products, how customers respond and how effectively it competes with established providers.
For now, its registration represents a new option for the market rather than proof that traditional banks will lose significant market share.
What Does the Registration Mean for Deposit Protection?
Deposit protection is an important consideration when choosing where to keep savings.
Revolut has announced that eligible deposits held under its New Zealand banking operation will be covered by the country’s Depositor Compensation Scheme, subject to the scheme’s rules and eligibility requirements. The scheme provides protection of up to NZ$100,000 for eligible deposits per depositor per licensed deposit taker.
Consumers should understand that this protection is not a guarantee covering every financial product offered by a bank. Eligibility depends on the nature of the deposit and the applicable rules.
Before transferring money, customers should read the bank’s official disclosure documents and confirm which accounts qualify for protection.
They should also understand the identity of the legal entity holding their money, the account terms and any conditions that apply to their particular product.
These checks are useful whenever a consumer considers opening an account with a new provider, regardless of how familiar the brand may be.
What Should Existing and Potential Customers Do Next?
People already using Revolut in New Zealand should follow official communications about the transition to its registered banking operation and any changes to the services available to them.
Revolut has said the transition for existing customers begins with the bank’s launch. Customers should check the company’s official New Zealand information to understand whether they need to take any action and which terms apply to their accounts.
Those considering opening a new account can take a few practical steps:
Compare savings rates, including the rate that applies after any introductory period.
Check account fees, eligibility requirements and withdrawal conditions.
Read the relevant product disclosure documents.
Confirm whether the specific deposit is covered by the Depositor Compensation Scheme.
Review customer support options and the process for resolving problems.
Compare the full offering with existing bank accounts before switching.
For customers considering borrowing, it is also important to confirm whether the relevant credit product has actually launched and to review the interest rate, fees and repayment obligations.
A New Chapter for Digital Banking in New Zealand
Revolut’s registration as New Zealand’s 27th registered bank marks a notable development for the country’s financial services industry.
Its plans for savings accounts and additional financial products could give consumers more options and encourage further competition. The company’s digital-first approach may particularly interest people who prefer managing their finances through mobile technology.
At the same time, customers should judge any bank on its products, service quality, transparency and suitability for their needs rather than relying on introductory offers or brand recognition alone.
The next stage will be watching how Revolut expands its services, how established banks respond and whether the new competition delivers lasting value for New Zealand consumers.
For Kiwi households, the arrival of another registered bank is a timely reminder to review savings options, understand deposit protection and make informed decisions about everyday finances.
FAQS
Has Revolut officially become a registered bank in New Zealand?
Yes. The Reserve Bank of New Zealand confirmed Revolut’s registration on 3 November 2026, making it the country’s 27th registered bank.
Will Revolut offer savings accounts in New Zealand?
Revolut has announced Instant Access Savings accounts, including an introductory variable rate for eligible new retail customers. Customers should check the latest official terms and rates before opening an account.
Will Revolut offer credit cards in New Zealand?
The registration creates a pathway for the company to expand its financial products, including credit-related services. Customers should check Revolut’s official announcements for confirmed availability and product conditions.
Are deposits with Revolut protected in New Zealand?
Eligible deposits may be covered by the Depositor Compensation Scheme, subject to its rules. The scheme provides protection of up to NZ$100,000 per depositor per licensed deposit taker for eligible deposits. Not every financial product necessarily qualifies.
Disclaimer: This article is for general news and information purposes only and does not constitute financial advice. Banking products, interest rates, fees, eligibility criteria and deposit protection conditions may change. Readers should consult official disclosures and consider their individual circumstances before making financial decisions.
Link to relevant NZ Indian Insights articles about personal finance, household expenses and smart money habits where appropriate.